
NCBJ Meets BAPCPA
Hon. Deborah L. Thorne, Northern District of Illinois
It is impossible to review the NCBJ’s last 100 years without recalling the turmoil sparked by the Bankruptcy Abuse Prevention and Consumer Protection Act of 2005. Signed into law by President George W. Bush on April 20, 2005, the law followed a decade of deliberation and is often attributed to lobbying by the credit card and banking industry—although debate exists about this. Many members of the House and Senate were convinced that obtaining a Chapter 7 discharge was entirely too easy and that many consumers with a measurably higher income resulting in disposable “excess income” should be forced to fund a Chapter 13 plan or do without bankruptcy relief.
The effective date of the new legislation was October 17, 2005, and as that date approached, courthouses around the country were flooded with new Chapter 7 petitions. Personal filings in October 2005 jumped by 50% to nearly 9,000 per day. Lines at courthouses resembled those for rock concert. Bankruptcy clerks, inundated with paper filings, used vacant courtrooms, issued bakery-style queue numbers and brought in additional staff to manage the surge as the effective date approached. Some debtors waited up to five hours to submit their petitions.[1]
Among its many changes, BAPCPA revised eligibility for Chapter 7 and directed that debtors capable of funding a Chapter 13 plan proceed under Chapter 13. To determine a debtor’s disposable income, BAPCPA used a “means test” with formulas to determine presumptive income and expenses. A Chapter 7 case in which the debtor had high enough presumptive disposable income under the means test was subject to dismissal for substantial abuse if the case was not converted. The means test also mandated minimum contributions to the plans of many Chapter 11 and Chapter 13 debtors
Before BAPCPA, dismissal for substantial abuse under § 707(b) rested on a bad-faith finding after notice and a hearing. Post-BAPCPA, § 707(b) defined “abuse” via the means test or, under § 707(b)(3), through a totality-of-the-circumstances finding of bad faith. BAPCPA prevented a Chapter 7 debtor from filing again for eight years, an increase from the previous bar of six years. Consumer debtors were required to take a credit counseling course prior to filing and another “instructional course concerning personal financial management” prior to discharge.
To address repeat filings, § 362(c)(3) provided that if a debtor files a Chapter 7, 11, or 13 case within one year of dismissal of a prior case, the automatic stay terminates 30 days after filing unless the debtor moves to extend and demonstrates good faith. If the new case is a third filing within one year, no stay will arise unless the court grants a motion to impose it. Both provisions carried a presumption of bad faith.
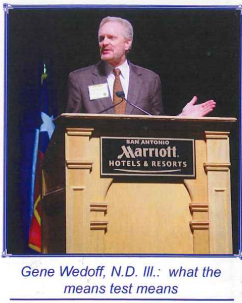
The sweeping changes demanded rapid implementation: new rules and forms had to be ready before the October 17 effective date. Judge Eugene Wedoff (NBIL-ret.) recalls 2005 as an exceptionally demanding year; he served as Education Chair for the NCBJ’s 2005 San Antonio conference while also serving on the Advisory Committee on Bankruptcy Rules.
That committee, chaired by District Judge Thomas Zilly, (WD Wash.) had only 180 days from the enactment of BAPCPA to create new rules and forms, including forms for the newly enacted means test. Separate forms needed to be created for Chapter 7, 13 and 11 debtors. Because of the short time between enactment and the effective date, only interim forms could be drafted. The working group that developed the Means Test forms included Eric Frank (prior to his becoming a bankruptcy judge), Mark A. Redmiles (EOUST) and Judge Wedoff. At its August 2005 meeting, just two months before BAPCPA became effective on October 17, the Rules Committee recommended that individual bankruptcy courts adopt interim forms proposed by the Committee.
After interim rules were proposed, many NCBJ members found that they became BAPCPA instructors and interpreters for the bankruptcy bar, helping all bankruptcy practitioners prepare as the effective date approached. NCBJ members wrote articles, conducted seminars and otherwise did their best to help educate lawyers, potential debtors and staff about the new law.[2] Preparation and enforcement was orchestrated in every district. Nearly 30 reported decisions discussing the “means test” were published by Westlaw during the 24 months post October 17.
The 2005 NCBJ Annual Meeting in San Antonio was held a few weeks after the BAPCPA effective date and was filled with judges and lawyers trying their best to master the new BAPCPA. Apparently, the final night’s dinner featured Wynonna Judd singing about the “good old days.” Perhaps she did not know about life before BAPCPA, but for many in her audience, that life was indeed the good old days and even 21 years later, many of us still yearn for it![3]
[1] Eric Dash, Debtors Throng to Bankruptcy as Clock Ticks, New York Times (Oct. 15, 2005), https://www.nytimes.com/2005/10/15/business/debtors-throng-to-bankruptcy-as-clock-ticks.html.
[2] See, e.g., Eugene R. Wedoff, Means Testing in the New § 707(b), 79 Am. Bankr. L.J.. 231 (2005); Eugene R. Wedoff, Major Consumer Bankruptcy Effects of BAPCPA, 2007 U. Ill. L. Rev. 31 (2007); Hon. Keith M. Lundin, Ten Principles of BAPCPA: Not What Was Advertised, 24 Am. Bankr. Inst. J. 67, 68–69 (2005).
[3] David G. Epstein, BAPCPA and Commercial Credit: Who (SIC) Do You Trust, 10 N.C. Banking Inst. 57, 57 (2006). The lyrics are in part as follows:
Grandpa, tell me ‘bout the good old days
Sometimes it feels like this world’s gone crazy
Grandpa, take me back to yesterday
When the line between right and wrong
Didn’t seem so hazy